Pension Maximization Plan
The Pension Maximization Plan (PMP) is an advanced retirement strategy designed to help retirees maximize their pension income while still providing strong protection for their spouse and family by utilizing life insurance. When retiring from a traditional defined benefit pension, you typically have two main choices:
- Single Life Option — You receive the highest possible monthly pension payment until you pass away, then your survivor receives 50% of your pension until they pass away. To get the other 50% of your pension for your survivor (spouse), you would have to select the beneficiary option below.
- Beneficiary Option — You elect a reduced monthly pension payment (often 10–20% lower for the rest of your life) so that the beneficiary of your choice will receive an additional percentage of your pension after your death, on top of the standard 50% to your survivor (spouse). Your pension often has 25% or 50% beneficiary options available.
Both options give your survivor (spouse) the standard 50% of your pension, but the beneficiary option is the only way to pass on your full pension. Many retirees choose the Beneficiary option to protect their spouse as much as possible, but this means paying for that beneficiary protection directly out of their pension income for the rest of their lives — even if both spouses live many years in retirement.
How the Pension Maximization Plan works is it allows you to elect the higher Single Life pension payment, maximizing your income while both you and your spouse are alive, and uses a specially designed life insurance policy to replace the beneficiary option. Upon your passing, the death benefit from the policy provides your spouse and/or beneficiary with a tax-free lump sum of money that can replace or exceed the traditional survivor benefit. In addition to that, the life insurance can also provide additional retirement income while both you and your spouse are alive.
Key Advantages of the PMP vs. Traditional Spouse Benefits:
- Higher retirement income while both spouses are alive — You keep more monthly pension dollars for travel, lifestyle, and enjoying retirement together.
- Living Benefits – Insurance policy can act as an additional source of retirement income
- No permanent reduction in your pension — You avoid paying for beneficiary coverage out of a reduced check every month for decades.
- Flexible, tax-efficient protection — The life insurance death benefit is typically paid income-tax-free and can be structured to provide ongoing income, a lump sum, or integration with estate planning.
- Potential for greater overall value — Many clients end up providing more total benefit to their spouse or next generation compared to a reduced joint-and-survivor pension.
- Legacy and flexibility — Any unused death benefit can support heirs, charitable goals, or other estate planning needs.
The PMP is especially effective when paired with conservative, permanent life insurance policies (such as indexed universal life and whole life) that build cash value and offer guarantees. At SD Mohn Insurance Services, we work with pension holders to analyze their specific pension options and design a PMP that aligns with their income needs, health, and legacy goals.
Pension Maximization Plan Example
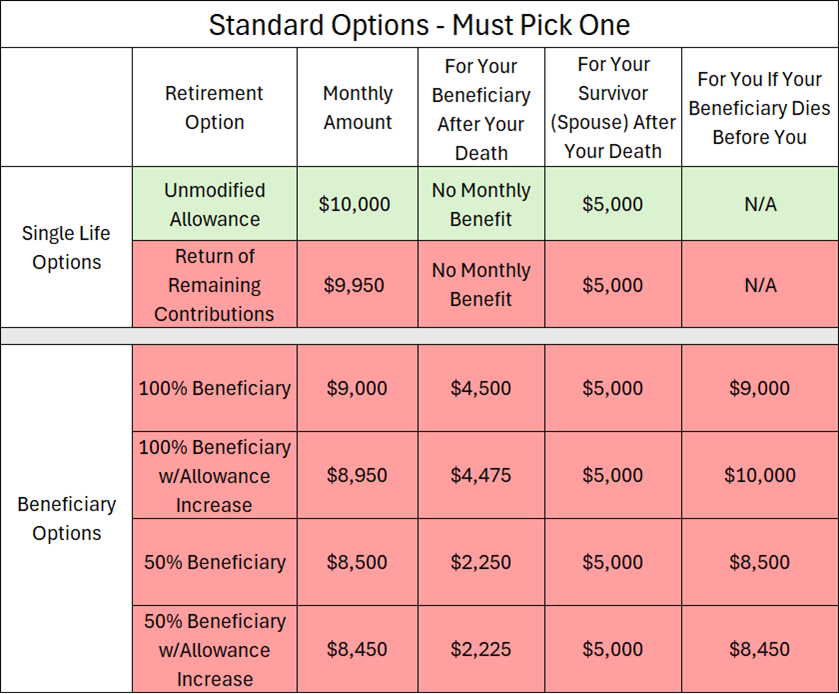
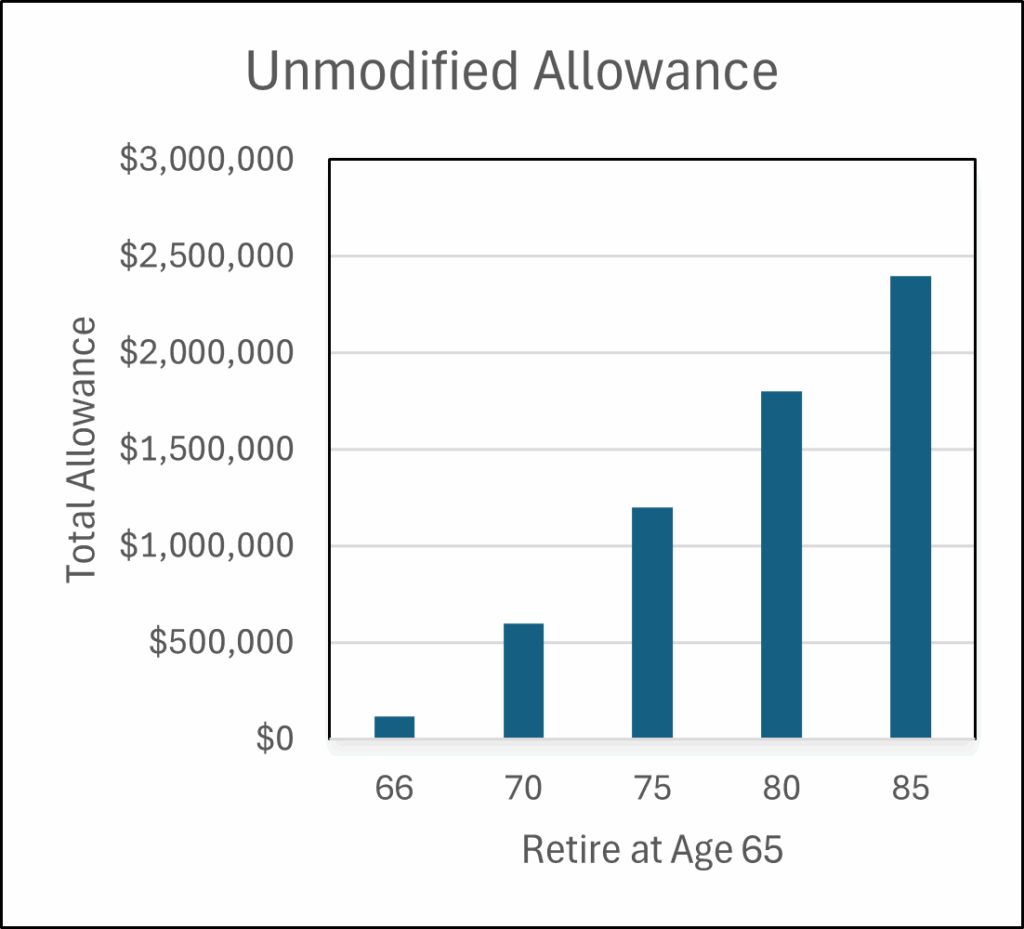
This chart is an example of what you should expect to see from a pension plan representative or from their online calculator. It shows the various options that cover you as the pension holder, as well as your beneficiary and survivor. The survivor, or spouse, automatically receives 50% of your total pension (unmodified allowance) if you pass away.
Our goal with the Pension Maximization Plan is to help you receive additional retirement funds beyond your full pension, while maintaining full control of your money and ensuring that your family is covered for any of life’s events.
In the examples below, we will show the differences between a beneficiary option and a PMP strategy.
100% Beneficiary Option
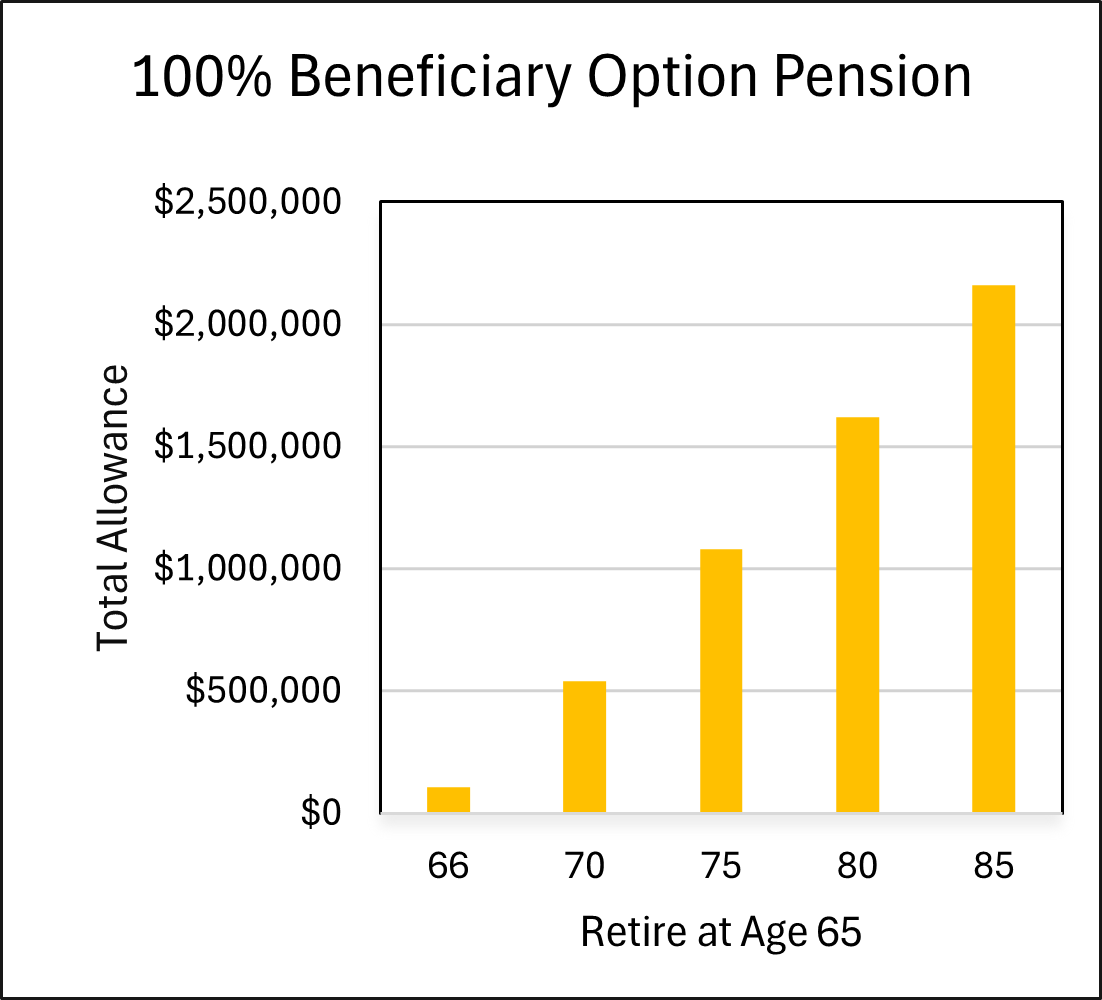
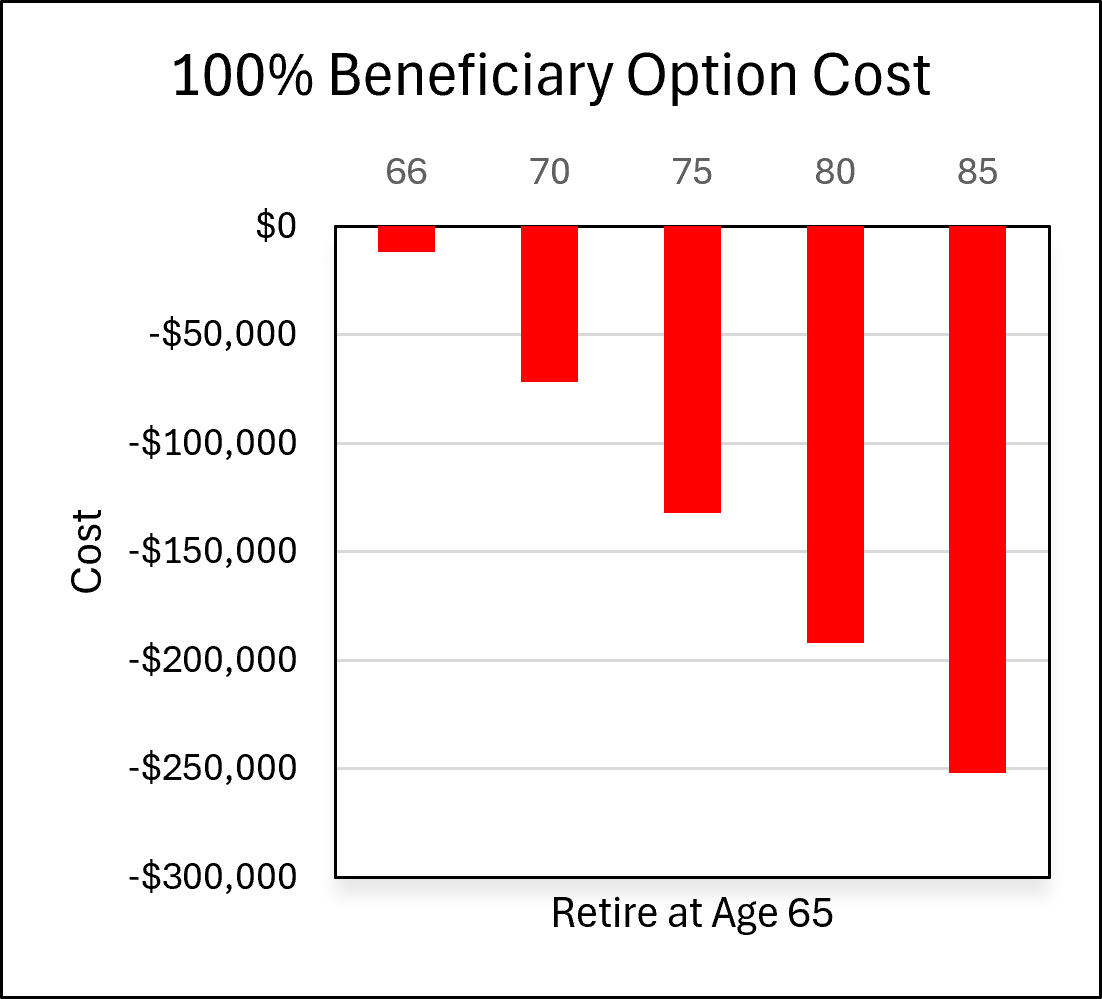
In the 100% Beneficiary Option, you receive the pension shown in yellow, totaling over $2 million dollars from retirement at age 65 until life expectancy at age 85. The cost of the beneficiary option is shown in red. You spent $240,000 for the option that was never used and you will not get that money back.
Unmodified Allowance + PMP
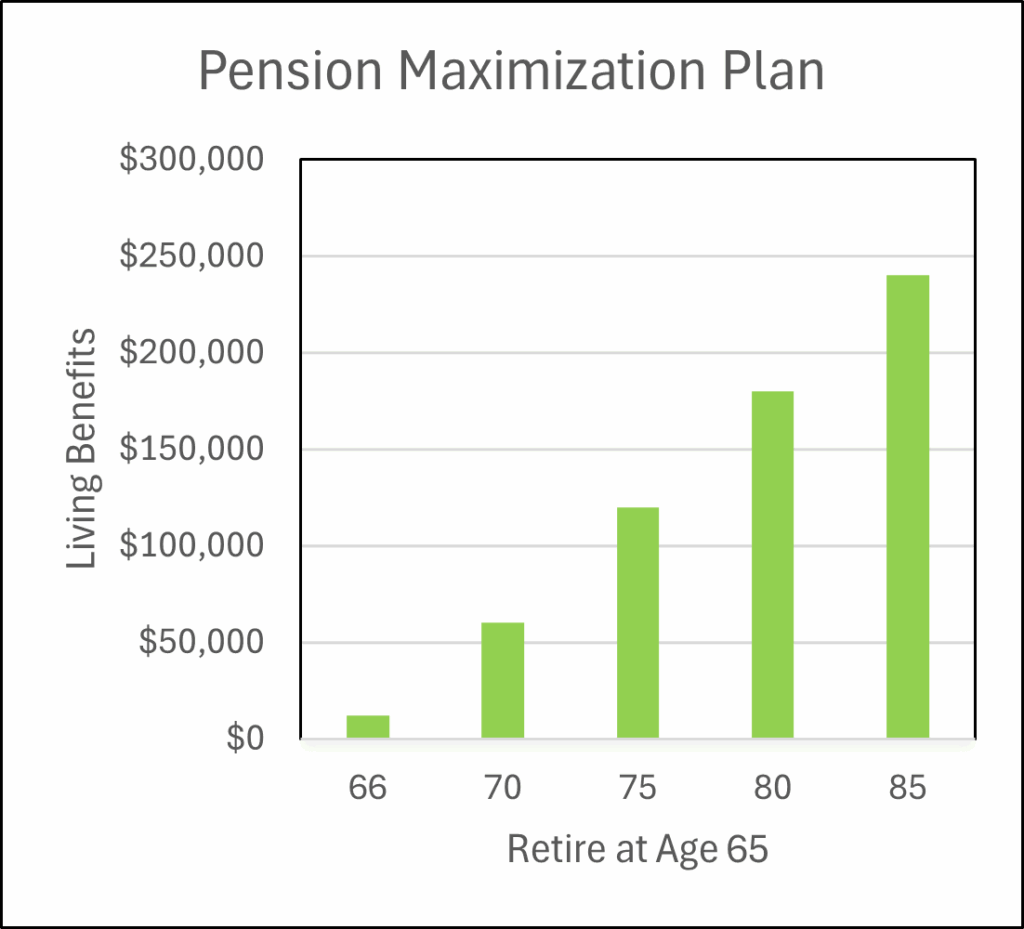
With this plan you receive your full pension, the unmodified allowance, and utilize the PMP with a permanent life insurance policy. The unmodified allowance vs the 100% beneficiary option gives you a $240,000 increase in your pension over the 20-year retirement period. On top of that, the life insurance provides two things: 1) a death benefit which covers your spouse or beneficiary if needed; and then the more likely scenario 2) a living benefit that you and your spouse can enjoy together. That additional income from the life insurance policy is distributed tax free at your discretion because the policy is 100% controlled by you. In this example we show that additional, tax-free income, as $12,000 a year, which is a total of $240,000 over the 20-year retirement period. The difference between the pension company’s beneficiary plan, and the PMP is just shy of a $500,000 of additional retirement income!! See the additional income in the charts below.
What does the Pension Maximization Plan Cost?
There are many variables to this question, but our goal is for it to cost LESS than the 100% Beneficiary option. Preferably, it should cost as little as possible while fulfilling all the needs of your retirement, but how do we accomplish that goal? The earlier the plan is funded, and the faster the plan is funded, the better the performance of the plan. It can be started as late as your retirement age, when you are forced to pick one of the standard options, but it is better to start it at the youngest age possible. The reason for starting younger is that the cost of insurance is less, and compound interest over time is used to maximize the benefits of the plan. Starting closer to retirement age will raise the cost of implementing the plan and decrease the time of compound interest which is what creates a larger retirement benefit. Funding the plan at a higher rate is a strategy that can be used to offset starting the plan later in life. Either way, the PMP is a better option than ANY of the beneficiary plans no matter when you start it! This must be in place, though, before you retire.
Why is the Pension Maximization Plan a better option?
The most noticeable difference between the plans is the additional retirement income. An equally important difference is the control of your retirement situation. A permanent life insurance policy is controlled by the person who owns it – you! Beneficiaries can be changed at any time, the funding of it is flexible if needed, and there are caps and floors to safeguard the policy from market fluctuations. The additional retirement money is also in your control – how much is distributed, and when, if at all. Life’s situations can change so having an adaptable policy that works with your life to improve it, instead of being an obstacle, is adventageous. Finally, having a diversified set of assets for retirement is one of the greatest strengths of this strategy. A typical diversified retirement portfolio should include your pension, 401k or 457b defined benefit plan, and a life insurance policy set up as a PMP.
Pension Maximization Plan
- Full Pension Received
- Maintain Full Control
- Additional Retirement Funds
- Assets are Diversified
- Death Benefit for Survivor/Spouse
Beneficiary Option
- Reduced Pension Received
- Control of Pension is Lost
- No Additional Retirement Funds
- No Living Benefits
- Money Lost to Pension Company